
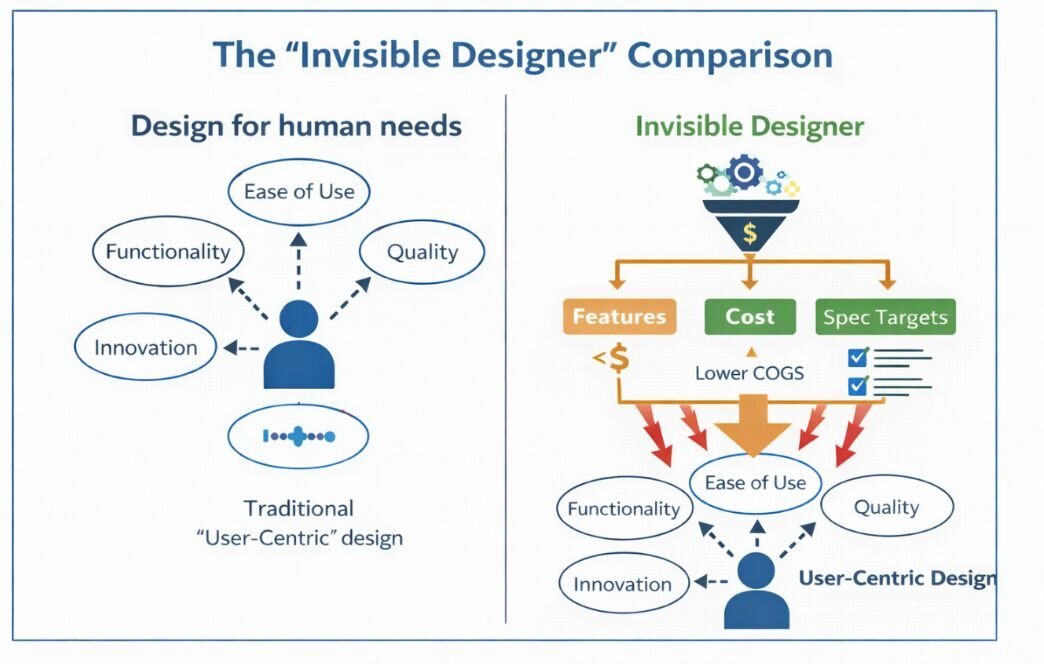
We are taught that product design flows from user needs. But in consumer electronics, this is increasingly a myth. There is an invisible designer in the room, and it isn’t human. The marketplace algorithm has become a key architect of hardware—quietly dictating specs, costs, and quality before a single CAD drawing even begins.
The real architects of product design today aren’t only the engineering team, the product manager, or even the CMO. It’s also the algorithm. Specifically, the ranking logic of digital marketplaces and the set of signals that determine whether a product lands on page one or disappears entirely. Before the real work even starts, the "rules of the game" defined by platform requirements have already created invisible design constraints that shape what gets built, at what cost, and to what standard.
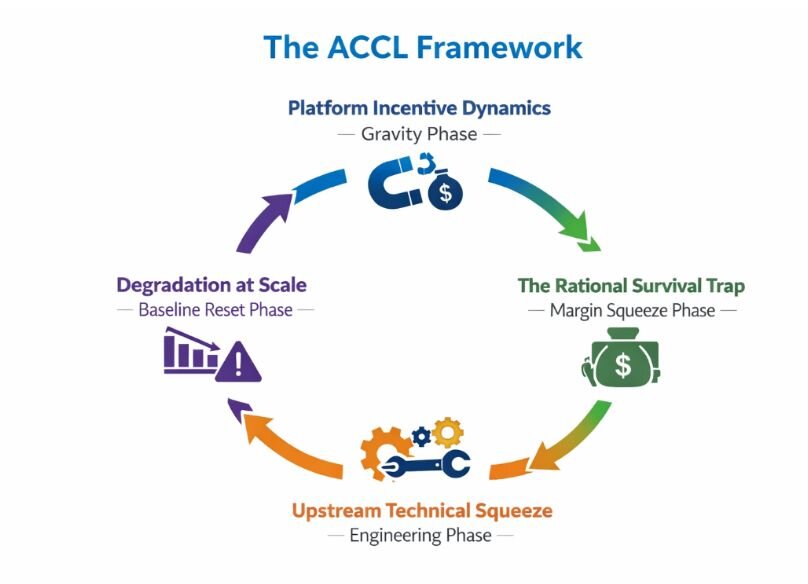
I call this the Algorithmic Cost Compression Loop (ACCL) and understanding it matters for anyone who makes, sells, or buys consumer electronics.
What gets rewarded
Digital marketplaces do not systematically reward innovation on its own merits; they reward the signals most closely tied to conversion.
Winning on a digital marketplace requires visibility. And visibility on digital marketplaces is defined algorithmically by factors like consumer ratings, sales velocity, price competitiveness, and conversion rate. These aren’t soft signals of demand; they are the hard math that determines whether a product reaches page one.
However, the issue is those factors systematically favor lower-priced products with just enough feature specification to meet consumer needs. The feedback loop shifts from “value-add” feature sets to “price-optimized” feature sets. In turn, core specifications have become the minimum viable specifications.
Far from being just one brand’s problem, this affects all sellers simultaneously. The effect transcends individual cost-cutting by resetting the equilibrium for the entire category.
The causal handshake from platform to factory floor
The mechanism unfolds across four stages, each one tightening the loop.
Stage 1: Platform incentive dynamics
The ranking algorithm creates what I think of as algorithmic gravity: a force driven by price, ratings, velocity and conversion that no seller can ignore, regardless of their product quality aspirations. This force dictates survival: if a seller prioritizes product quality over algorithmic optimization, they lose visibility or spend on digital marketing to buy their placement on page one. In a vast marketplace, no visibility means non-existence.
Consequently, the rational move is to cut margin and demand lower manufacturing costs. Because every competitor experiences the same gravitational pull, products eventually start looking and costing the same, shifting differentiation from the product specifications to the storytelling.
Stage 2: The rational survival trap
The margin squeeze then travels upstream. Sellers facing mounting pressure to drive visibility are pushed to reduce prices, discount frequently and deeply, and strip differentiating specifications. That survival trap manifests on the manufacturing side as a non-negotiable COGS target.
Stage 3: Upstream technical squeeze
In fiercely competitive categories, manufacturers have increasingly moved toward lower-cost solutions. Let’s take the example of a simple charger: GaN-on-Silicon substrates—more affordable, but less thermally resilient than the alternatives. We see a systematic shift toward lower-cost solutions where thermal resilience is often traded for a sub-$10 factory floor price.
Stage 4: Degradation at scale
Compressed, low-cost products become the category baseline. Consumer expectations reset to a new normal with a lower bar. R&D budgets get gutted by "cost-down" requirements and true innovation takes a backseat to minor form factor changes. Critically, this structural commoditization is not a one-and-done cycle. It reinforces the algorithmic loop, making price gravity even stronger as value differentiation disappears.
The implications reach further than a bad charger
The "so what" may sound simple—that consumers should expect cheap electronics with mediocre quality. But the causal handshake from digital platforms to factory floors reaches well beyond the average consumer purchasing their next power adapter or hair dryer online.
Consider the middle of the market. In this race to the bottom, the innovative mid-sized brands—those that lack the scale of commodity giants or the margins of luxury tiers—are under mounting pressure. Market observers across consumer electronics have begun noting a growing polarization: the category is consolidating toward two poles, low-priced commodity products and premium luxury products, with the innovative middle increasingly hard to sustain.
Then there's the sustainability dimension. Cost-down engineering leads to short product cycles, as sellers chase time-to-market and volume targets. The result is accelerating landfill waste. A few consumer electronics brands have differentiated on environmentally friendly materials and durability—see Nimble's impact model as a prime example—but they're the exception, not the rule, and the algorithmic economics actively work against their model.
Finally, there are genuine safety implications. Margin pressure leads to cost-cutting across the entire development process, including the rigor of third-party testing and certification. Cutting corners on testing labs to get a product to market faster and cheaper isn't hypothetical. It's a predictable output of the loop, and it increases risk for end users in ways that aren't visible at point of purchase.
Breaking the loop
It is one of the more striking paradoxes of the current consumer electronics landscape that more products and more sellers in the market actually produce less differentiation and less innovation. The perceived abundance of customer choice often masks a structural convergence, where products are built to satisfy the channel’s math rather than the consumer’s diverse needs.
Breaking the loop requires either a platform-side intervention or a brand-side bypass. On the platform side, this means ranking logic that weighs durability and quality signals more heavily. On the brand side, it means investing seriously to develop a well-respected brand and Direct-to-Consumer reach, where rules of the game are set by the brand, not the algorithm. More than just a margin play, DTC is a structural escape from algorithmic gravity.
Industrial policy also has a critical role in counteracting the algorithmic pressures through incentive structures that reward innovation and quality over the long-term through procurement standards or right-to-repair legislation. Breaking the loop, however, is not easy because it is driven by rational behavior across each node: platforms optimizing for conversion, sellers for visibility, and manufacturers for margin. No individual actor is making a bad decision; the problem is the system itself, not its individual participants.
But recognizing the loop is the first step toward breaking it. As long as product strategy frameworks treat the end user as the primary design stakeholder while the algorithm quietly makes the real decisions, the compression will continue, and the products on page one will continue to converge toward lower-cost, lower differentiation outcomes.
The ACCL turnaround playbook
To effectively disrupt this algorithmic gravity, a product manager must deeply assess where their product sits in the ecosystem of brand equity. If you are a tier 1 legacy brand with high consumer awareness (e.g., Apple), you are partially insulated from algorithmic gravity because a large percentage of your traffic comes from branded search due to the inherent brand loyalty that exists apart from the platform.
But if you have engineered a high-quality, high-spec product within a brand umbrella with low visibility, your traffic is dependent on unbranded discovery search (e.g. generic words like “65W GaN charger”) creating high exposure to the algorithmic gravity. When low-cost, low-quality competitors flood the marketplace and trigger the ACCL, a PM cannot just sit tight. To break the loop, they must execute an aggressive, three-pronged counter-offensive.
The case study below reflects this three-pronged approach.
Context: Let’s assume our PM team launched a pair of premium, wireless active-noise-cancelling (ANC) earphones with an MSRP of $249–a high quality product under a brand with low visibility.
The friction: Four months post launch, key ecommerce platforms witness an influx of less-expensive, sub-$100 ANC earphones. These competitors used cheaper drivers that sound muddy but utilize aggressive, keyword-stuffed listings and review generation tactics to simulate high quality. The marketplace does not understand the superior sound quality and premium materials of our product; it recognizes the massive price delta and immediate conversion spikes on the cheaper options. The algorithm systematically pushes our product listings from page one to position #34, and because our sales relied heavily on discovery search, our daily volume plummeted.
The playbook: Instead of permanently being relegated beyond page one or degrading our internal components to match lower costs and specifications, we initiate a three-pronged high-velocity turnaround strategy.
Phase 1: Feed the algorithm
We temporarily drop the retail price roughly from $249 to slightly higher than $100 to demonstrate superior value and better feature sets while still remaining within approachable pricing. This intentional price cut instantly satisfies the algorithm’s bias for conversion optimization, triggering a 4x spike in daily unit sales velocity and rocketing the search ranking to page one.
Phase 2: Hijack the traffic
We know that the near-$100 price point is unsustainable for our business model long-term and we overhaul our search listing with rich video content, showcase the premium unboxing experience, and initiate a post-purchase digital campaign titled “The True Cost of Sound” to educate new buyers on the superiority of our product, while building trust.
Phase 3: Unlock upstream volume effect
While the narrative blitz is building affinity, we pass the verified 4x sales velocity data to our Tier-1 acoustic component factory, while simultaneously tearing down competitive products to identify potential cost savings with little to no impact to product quality. Because we cross into larger volumes, we negotiate a cost reduction on components like the chipsets, temporarily stabilizing our compressed margin while brand equity takes root.
The final outcome:
Because we leverage the high velocity window to build intense brand loyalty, educate customers on differentiation, and drive an onslaught of organic, verified 5-star reviews, our marketplace dynamics fundamentally shift. Discovery shifts over to a high volume of branded search, and our lower costs from volume-based demand improve overall margins while reducing dependence on the algorithm. Over time, this playbook, though costly in the short-term, establishes long-term equity for the product and the brand, shielding us from long-term degradation.
